

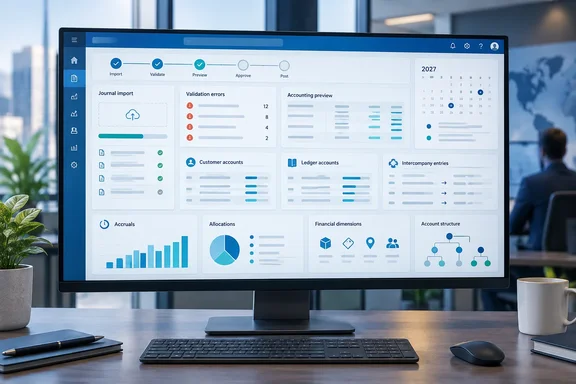
The immediate message for Dynamics 365 Finance administrators is less “enable a new feature” than start assessing the prerequisites now. Microsoft says the capabilities require optimized financial dimensions and the Ledger posting rules framework, but the roadmap entry does not identify configuration steps, migration tooling, licensing implications, supported journal types, or whether existing custom journal integrations will need changes.
That omission is significant. Journal processing is where master-data rules, workflow controls, integrations, tax, and period-close policies meet. A new workspace can reduce clicks, but it can also expose old assumptions in custom imports and financial-dimension design that users have been working around for years.
The planned journal changes reach beyond a new import screen
Microsoft’s roadmap describes a consolidated set of functions rather than one isolated journal enhancement. Finance users are expected to work with both customer and ledger account types, import journals, and review import errors without moving to the Data management workspace. They will also be able to preview accounting generated by intercompany and intracompany activity, accruals, and allocations before posting.
Today, Dynamics 365 Finance supports several ways to bring journal data into the application, including Data Management Framework processes and Excel-based publishing. Microsoft’s current Learn documentation says journal lines published from Excel are validated against the financial-journal rules in the environment, after which users can edit or post the vouchers inside Finance. That is useful, but it does not eliminate the administrative divide between data import, error remediation, and journal review that the new roadmap item appears intended to narrow.
The practical value of moving import-error review closer to the journal depends on the errors it exposes. A rejected file because a column is malformed is a data-preparation problem. A rejected journal because a default dimension, account structure, tax configuration, posting restriction, or derived rule produces an invalid combination is an accounting-configuration problem. Microsoft has promised the former will be easier to review in the journal experience; it has not yet said how deeply the new error view will explain the latter.
For finance operations teams, that distinction should guide testing. A cleaner error list is helpful, but the more material improvement would be diagnostics that identify the exact line, account, dimension source, and rule responsible for a failed validation. The roadmap does not commit to that level of detail.
Preview before posting changes the control point
The most consequential part of the announcement is the promised ability to preview intercompany and intracompany accounting, accruals, and allocations before posting. Those are areas where an apparently valid source journal can generate a more complicated set of downstream ledger entries.
Microsoft’s existing documentation already emphasizes that general journals rely on detailed configuration. Journal names can set defaults for offsets, currency, and financial dimensions, while workflow approval can impose review and approval steps. Accounting structures and advanced-rule structures determine which financial dimensions are valid and required as a user enters a journal. Microsoft also documents that default and fixed dimensions can behave differently during entry than they do when a voucher is posted.
That last point matters. In the current product, a journal line can display one dimension value during entry while the posted accounting entry reflects a fixed value applied during posting. Microsoft’s guidance on financial dimensions warns that values are assembled from multiple places—journal headers, customer or vendor records, ledger settings, main accounts, and derived rules. A pre-posting preview has real control value only if it represents the accounting result after those rules have been applied, rather than merely echoing what appeared on the source journal line.
Microsoft has not published technical documentation for the Ledger posting rules framework named as a prerequisite, nor has it described whether the preview will show every generated balancing, due-to, due-from, tax, rounding, or allocation entry. Until those details arrive, organizations should not assume a preview substitutes for a controlled test company or a reconciliation process. It is best understood as a planned earlier checkpoint in the posting workflow.
Customer accounts in journals broaden the validation burden
The roadmap explicitly calls out customer and ledger account types. That is a meaningful detail because it places customer-account behavior in the same planned journal-processing flow as direct ledger postings, where defaulting and dimension behavior can vary substantially.
Microsoft’s documentation for financial journal defaults explains why this is not a cosmetic difference. When a journal line uses a ledger account, the application can apply the relevant main-account default or fixed dimensions during transaction entry. With customer, vendor, bank, fixed-asset, or project accounts, the final main account may not be known at the same stage. During posting, the application evaluates the accounting entries and applies fixed dimensions where required.
In other words, a journal that looks complete at entry can still change when it becomes posted accounting. Any new import-and-preview process must therefore be evaluated against realistic account combinations, not only clean ledger-to-ledger test journals.
Finance teams should build a test pack before the preview becomes available. It should include customer-to-ledger and ledger-to-customer journals; accounts with fixed dimensions; journals with header-level defaults; derived-dimension rules; tax-relevant transactions; intercompany postings; and lines that deliberately fail validation. That is the quickest way to establish whether the new interface improves visibility into the business rules that actually govern posting.
Future-period accruals will stop forcing periods open
Microsoft also says future-period accruals will no longer post automatically, reducing the need to leave future fiscal periods open. This could be a valuable control improvement for organizations trying to close periods promptly without blocking the preparation of planned accrual activity.
Leaving future periods open can be operationally convenient, but it creates a wider window in which transactions may be posted to periods that finance teams regard as not yet ready. Microsoft’s roadmap wording suggests the planned behavior will separate creating or scheduling an accrual from automatically posting it into a future period. The entry does not explain the replacement process: whether users will need to initiate posting manually, whether a batch process will do so after the period opens, or how the change interacts with recurring and reversal journals.
That gap needs an answer before December 2027. A change that prevents automatic future posting may strengthen period control, but it could also introduce a new manual close task if scheduled accruals do not resume predictably. Controllers should ask their implementation partners and Microsoft account teams for the eventual design of approval, batch execution, exception handling, and audit-trail behavior—not merely confirmation that automatic posting has stopped.
The prerequisites are the real implementation work
“Optimized financial dimensions” and the Ledger posting rules framework are not minor switches for every tenant. Microsoft’s existing Finance guidance makes clear that financial dimensions feed account structures, advanced rules, default values, balancing logic, reporting, and journal validation. Dimension configuration can also have performance consequences, especially where organizations use large and complex sets of account combinations.
The roadmap says those prerequisites are required but does not say whether customers must adopt a new feature flag, convert legacy dimension data, rebuild configurations, or redesign existing posting controls. It also does not identify whether the requirement applies to every journal scenario in the release or only to the new experience.
Administrators should inventory the current state of their chart-of-accounts architecture now: active dimensions, account structures, advanced rules, fixed dimensions, journal controls, posting definitions, Excel templates, Data Management entities, and custom extensions that create or post journals. They should also identify integrations that rely on imports being handled through the Data management workspace, because a new in-application error-remediation path may alter operational runbooks even if the underlying data entities remain supported.
Microsoft has provided a long runway—roughly six months to preview and more than a year to planned general availability. The concrete consequence is that this should be treated as a 2027 finance-platform change program, not as a late-cycle user-interface update.